Waiting on Washington
2/11/26 US/Global DeskBig weekIwo Wojcik US The Fed is running out of leeway. This Wednesday, policymakers voted on holding rates at 3.75% to 4%, although the decision came with two dissenters (Hammack and Cook) who both favored a 25-bp hike. Kevin Warsh called this a "family fight," but what came from the meeting was the message that inflation is still a problem. After the meeting, markets put the odds of a hike in December at 82.6%, although at market close on Friday, the probability dropped to 70.7%. And I find this move more interesting than the actual percentage. Think about it: what happened between Wednesday and market close? Alphabet had its worst day ever. Amazon's $42.4 billion cash flow deficit, and the Nasdaq having its worst month in over a year. This will be all talked about in more detail in the U.S. equity section. It seems like the market spent the end of the week pricing in a slightly less hawkish Fed, not because inflation is cooling, but because the big companies that drive the market are starting to crack. And new data this week isn't making the Fed's job a whole lot easier. The Q3 GDP report came in at an annualized 3.4%, an increase from 2.2% in Q2, and beat expectations. As well, first they showed us September's PCE, which rose to 3.6% year on year from 3.4%. Core PCE, which strips food and energy, showed 3.1%, so it gives an interesting split. The economy is still growing strongly, but inflation moves further away from the Fed's 2% target. And our favorite topic yields, they fell again. The 10-year fell below 4.95%, down around 5 basis points on the week. This continues the common theme of investors moving away from corporate bonds and other assets back towards government bonds, seeking safety. 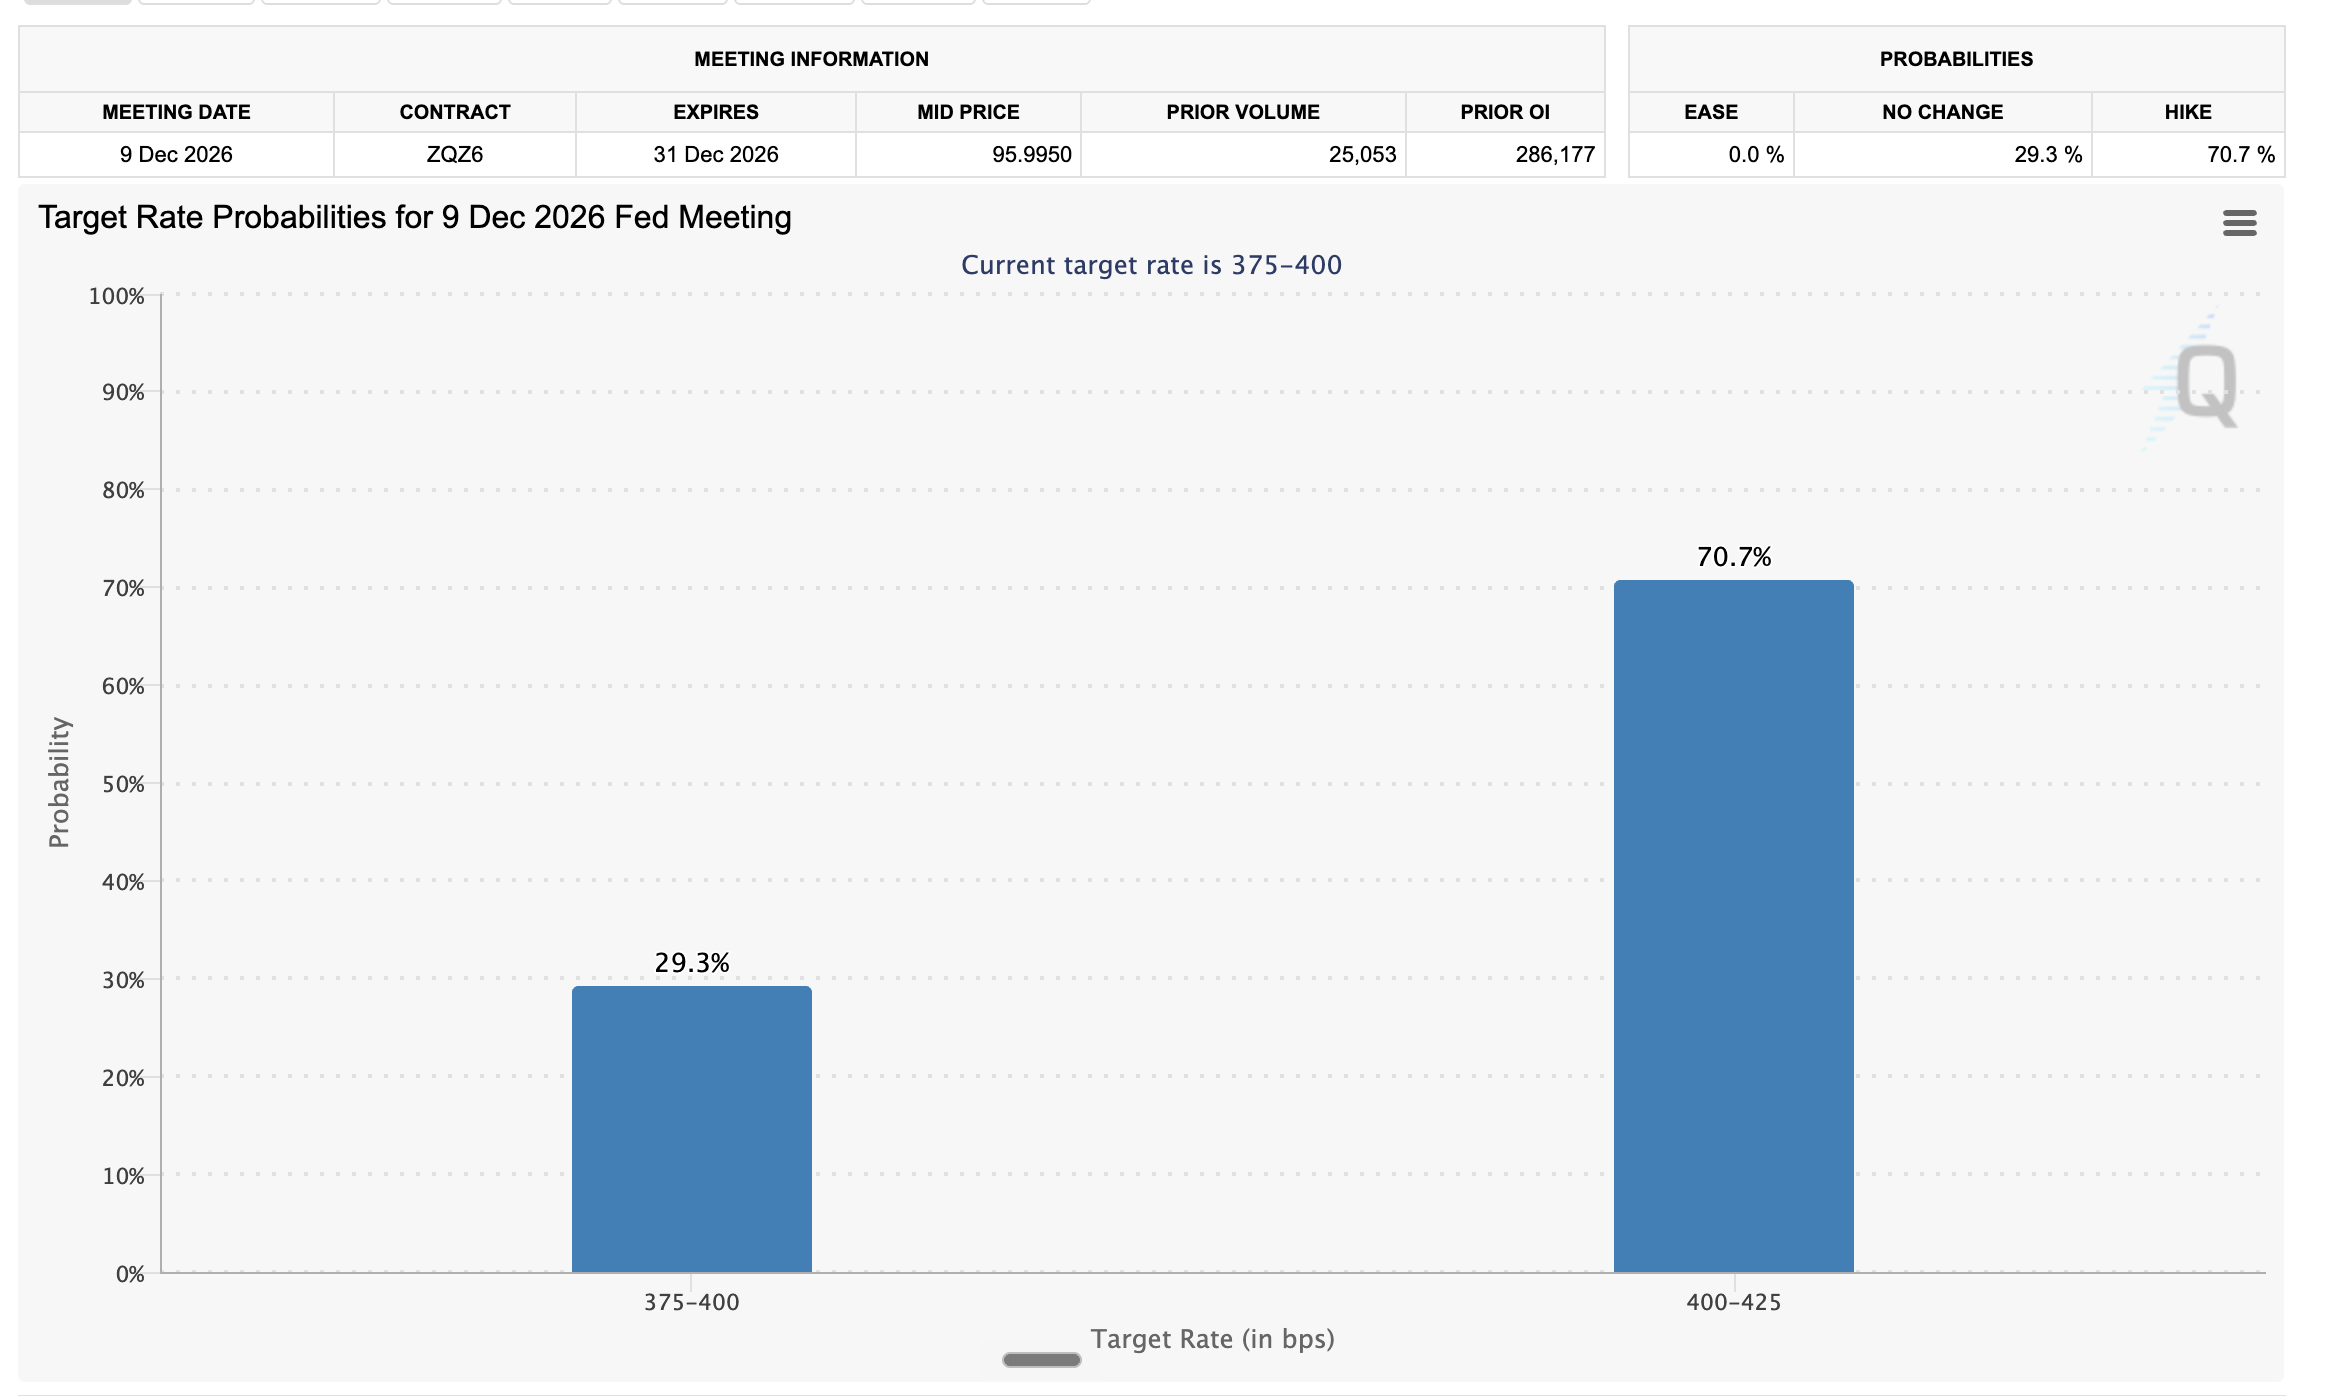
Interest rate probability- cmegroup.com US Equities This week, it's cash flow. We had four major tech companies report earnings, and the common theme seems to be investors asking how much cash all this AI spending is actually generating. Microsoft did well. Cloud revenue reached $63.9 billion, up 30%, while Azure grew 48%. Even though there was heavy spending on infrastructure, it did generate $18.6 billion in free cash flow. Then we saw a full 180 for Alphabet. Despite strong cloud growth, it showed weaker search results and $51.4 billion in quarterly capital expenditure. Their shares were sent down 12.6%, the worst day the company's history. Amazon shares also fell around 3.8% on the week. Even though AWS revenue grew 39%, their free cash flow over the past 12 months turned negative by 42.4 billion. It's clear investors are looking past questions such as "Is demand for AI still existent?" They're now laser-focused on whether the returns will justify the humongous spending. The Nasdaq also had its worst month in over a year. Alphabet alone lost hundreds of billions in market value. I think my favorite story of the week was that while tech companies were being punished for spending billions, energy stocks are reaching record-high profits. The quarterly profits for U.S. companies have reached an estimated $67 billion, the highest point since the Ukraine war. Exxon Mobil reported $15.4 billion in Q3 profit, more than double what it earned during the same period last year. While big oil is raking in huge profits, you're paying for it with high gas prices. Global North Korea, what have you done? Binance suffered what blockchain analysts are calling the largest crypto theft on record. On the 29th of October, around $6.36 billion was moved out of wallets, with most of these transfers happening in around 20 minutes. TRM Labs linked this to North Korea's TraderTraitor unit. Binance says it pledges to cover losses. This incident just highlights the security risks that come with crypto's growing influence in global finance. In Israel, we saw general elections this week. Although no clear winner has been produced yet, Netanyahu's party secured 53 seats against 48 for the opposition party run by Gadi Eisenkot. So far, neither party has reached the 61 seats needed for a majority. Keep a close eye on these elections, as they have the ability to shape what happens next within Iran and other conflicts that Israel is involved with. UAE/Gulf DeskThe Hedge That Didn'tHenry de Salis It's getting a bit tiring writing the same thing: the Houthis launch some missiles, oil goes higher, and Gulf markets slump. The war definitely sits in the same, slowly escalating, position, waiting for Washington to make a move after the midterms. So let's look at the interesting stuff: gold went through the floor, America bought a stake in Mubadala, and diplomacy looks a little optimistic. 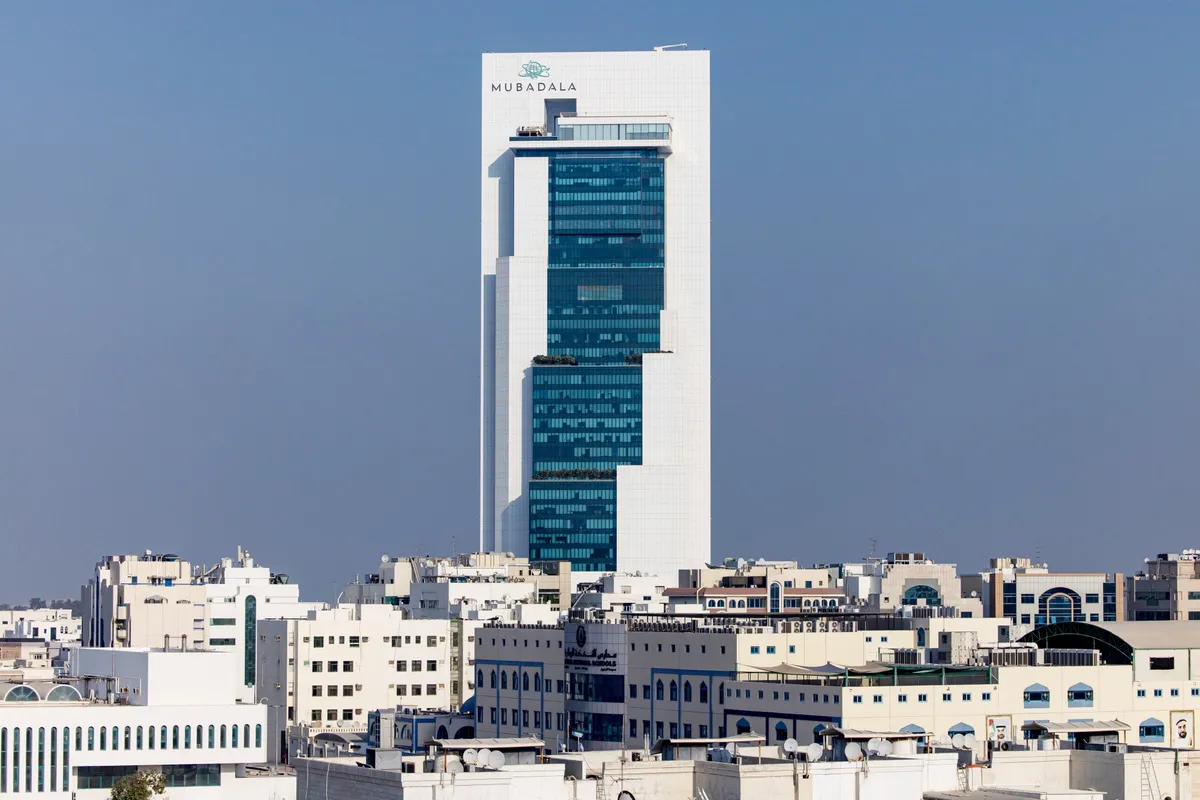
Mubadala HQ, Abu Dhabi, Bloomberg The Gulf, The War, and The Slump With tankers stuck, being struck, oil closed October at its highest since April, up 13.6% on the month. Gulf OPEC+ producers are still pumping well below their targets, Houthi missiles are being fired at Saudi oil targets, and Hormuz is still open or closed depending who you ask. Gulf central banks followed suit with the Fed's decision to hold rates, with the next move likely to be a hike. Dubai was seen up 0.6% for the week, while Abu Dhabi lost 1.3%, as Saudi snapped an eight-week losing streak. Brent's December contract settled at $117 on Friday after another tanker attack in Hormuz, although diplomacy has been looking better, as Qatar officials went to Tehran. A proposal was discussed letting the strait fully reopen within two days, although Scott Bessent says transits are back to pre-war levels excluding Iranian barrels. In Saudi, the Houthis claimed six attacks on Thursday, including Ras Tanura, Abqaiq, and Rabigh. Neither Riyadh nor Aramco confirmed damage, though a fire was quickly contained. OPEC+ is likely to hold quotas in December. That means nothing because they don't even hit them anyways. America Goes Shopping On Monday, Apollo took a minority stake in Mubadala Capital, reportedly near 10%, encompassing $5bn of commitments from Apollo and other investors. On other business news, the Binance theft (discussed in the US/Global desk) actually hit Abu Dhabi, as the founder, Changpeng Zhao, lives there, and ADGM's regulator is engaging closely with the exchange, as MGX also invested $2bn in March 2025. Abu Dhabi has spent years pitching itself as a capital of capital and also for crypto though, and Apollo's cheque says the first might be true, but Binance is definitely a test of the second. Gold: the Hedge That Didn't December Gold settled at $3,898 on Friday, down 3.3%, with spot at about $3,875. That's the lowest in a year and roughly 31% below January's record of $5,595. As we've discussed before, gold is supposed to be a hedge, but thriving inflation hits a metal that doesn't pay any interest. Even worse for gold, the Dollar is also subsequently quite strong at the moment, despite all the headlines surrounding the debasement trade. A Gulf Waiting Just like last week. We're still waiting for the midterms. As an Abu Dhabi resident myself, things are calm, continuing as normal, but there's definitely a lot waiting on what Washington decides to do after the midterms. Rubio spoke last week, suggesting that Trump hasn't decided on whether to pursue any further Iran strikes. On the upside, it's fair to suggest that Qatar's push for diplomacy has yielded some interesting results, with the rapid re-opening plan discussed last week, and Trump's hesitation to restart strikes probably plays into the idea that a diplomatic outcome is entirely possible. Or, most likely, the same grinding half-conflict that has been going on for more than six months. Read online at twodesksnewsletter.com This is not financial advice. Read our disclaimer.
Henry de Salis 
Copyright 2026 Two Desks. All Rights Reserved. |